The WHY is why they BUY
Blog
-
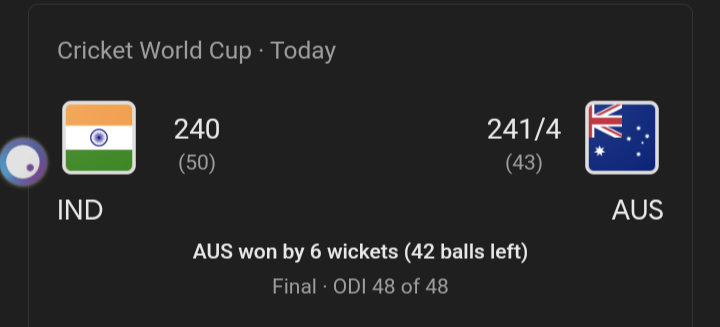
ICC Cricket world cup
They both have skill. But Grit changes the game.
GRIT + SKILL = WIN
Keep sharpening that axe ?
-
Working hard on the right things
Exerting more effort doesn’t help if you’re on the wrong trajectory.
– Working harder on the wrong thing just wastes more time.
– Learning more from a biased source will lead you further from the truth.
– Doubling down on a toxic relationship only sets you up for more headaches.
Before you try harder, make sure you are walking a path that leads where you want to go.#jamesclear
-
Death from overfunding: An obituary for Convoy
The death of Convoy has been one of the biggest stories in both tech and freight media over the past week. While the freight market has suffered a number of major shutdowns, few were as sudden as Convoy’s.
After all, Yellow was a much bigger company, but it died a very slow death, and because it was a publicly traded company, we all got to watch its journey on life support for many years. Convoy’s story, on the other hand, offers a cautionary tale of a meteoric rise to burnout in just eight years. For most of that time, it was respected, loathed and feared by industry insiders, both wary and weary of how a war chest of capital can disrupt the economics of the industry.
For a few years, that’s exactly what happened.
Blitzscaling
In Convoy’s earliest years, it used venture capital that it raised to “buy market share.” It offered shippers that agreed to be early adopters rates that were cheaper than market — discounted significantly compared to the rates of incumbent players.
This worked; some would say too well. Convoy was able to scale quickly and garnered significant market share from some major shippers along the way.
At first, Convoy offered shippers aggressive discounts on their major lanes and then used that wedge to get access to lower-volume lanes. This allowed the company to expand its margins in secondary lanes, offsetting losses in the primary lanes.
The growth story was impressive and investors became excited about the potential of how big Convoy could become. After all, if this story could play out with more shippers, the company would eventually become a massive multibillion dollar firm — perhaps the biggest logistics firm on the planet.
Early on, the company focused on blitzscaling — a term coined by Reid Hoffman — which means to prioritize growth at all costs. After all, Hoffman was one of Convoy’s first board members and likely set the tone of its operating playbook.
In Hoffman’s view, “You must win first prize to survive in the internet era,” because in the internet age, markets are built on “winner-take-all” outcomes.
Hoffman coined the term after studying high-growth software and platform businesses, where the unit economics were incredibly favorable to the scale of the business. His own experience building LinkedIn and PayPal had informed these lessons.
In a series of quotes in “Blitzscaling: The Lightning-Fast Path to Building Massively Valuable Companies,” Hoffman characterizes his theories that many observers of the Convoy story will recognize:
“You don’t necessarily need to have solved your revenue model before deciding to blitzscale. In fact, a key element of blitzscaling is often the willingness of investors to fund growth before the revenue model is proven — after all, it’s pretty easy to fund growth after the revenue model is proven.
“To achieve massive success, you need to have a big new opportunity — one where the market size and gross margins intersect to create enormous potential value, and there isn’t a dominant market leader or oligopoly. A big new opportunity often arises because a technological innovation creates a new market or scrambles an existing one.
“Blitzscaling is a strategy and set of techniques for driving and managing extremely rapid growth that prioritize speed over efficiency in an environment of uncertainty. Put another way, it’s an accelerant that allows your company to grow at a furious pace that knocks the competition out of the water.”

(Photo: Jim Allen/FreightWaves) Convoy’s management and board believed that cash burn wasn’t a concern. As long as it could grow and expand margins, future investors would bid up the company at even higher valuations. After all, it was going to blitzscale its way to market domination.
The company was founded and scaled in a period when venture capital was incredibly easy to attain and everyone wanted a piece of disruptive businesses that were displacing incumbent players. Articles that covered the company early on compared its mission to what Uber had done to the taxi industry and many believed that the opportunity for Convoy was even bigger.
Prospective investors, realizing that the company was subsidizing some of its growth through shipper discounts in the early part of the relationship, looked for a metric that they could get behind.
Traditionally, freight brokerage valuations are measured on a multiple of EBITDA. But for a company that was prioritizing blitzscaling, investing in its platform and network incentives, that wasn’t possible.
So the investors that bought into the story decided that gross revenues were a sufficient metric for underwriting. If the company could continue to scale up, margins would eventually increase.
After all, if it prioritized short-term profits, it was sacrificing growth and building out a platform that could displace the incumbent players.
Nothing but net
Freight brokerages have historically reported two revenue numbers: gross revenue and net revenue. Traditionally, it was the scale of net revenues that mattered; gross revenue was a vanity statistic that everyone bragged about but was largely ignored.
When venture capital firms (and the growth equity firms that followed) began investing in digital brokerages, the startups somehow were able to convince the investors that gross revenue was the appropriate metric for valuation. That was the first and key mistake; the VCs underwrote the businesses on gross revenues. The second mistake that investors made was treating Convoy like it was a tech company and not a logistics company.
Years ago, I asked an investor who worked for a very large growth equity firm that happened to be one of C.H. Robinson’s largest investors why he also invested in Convoy. He told me that as Convoy scaled with individual shippers, there were increased margins on the freight. Also, as Convoy increased volume on a particular lane, it drove down the purchased transportation cost.
My conversation with that investor was in September 2018, right after Convoy announced a $185 million capital investment at a $1.08 billion valuation. At the time, I wondered if Convoy benefited from the early phase of a softening freight market, when margins naturally expand for brokers.
From conversations over the past few years about Convoy, it was clearly understood by industry insiders that Convoy was valued far differently by venture capitalists than was the accepted norm for the industry.
The group bidding up Convoy’s valuation included some of the most iconic names in technology and Wall Street, including Jeff Bezos, Bill Gates, Marc Benioff, Henry Kravis, Google’s venture arm, Fidelity and T. Rowe Price.
When the company continued to raise capital at even higher valuations, it created a great deal of bewilderment about how the company could defy the valuation economics of a very traditional — some would say boring — industry. When challenged, defenders would mention Amazon’s or Tesla’s valuations in their early days. In the mind of investors, Convoy had the same breakout potential.
All of this created a high level of resentment from industry incumbents. But for the investors, Convoy offered a chance to build a business in one of the largest and most fragmented industries on the planet: the North American trucking industry.
The company ended up raising two more rounds of financing. In November 2019, it raised $400 million at a valuation of $2.75 billion, and in April 2022, it raised an additional $410 million at a valuation of $3.8 billion.
In addition to raising capital from investors, Convoy also raised debt from banks and financial firms that the company leveraged to achieve even faster growth.
The company seemed unstoppable.
(Photo: Jim Allen/FreightWaves) So what happened?
Over the past few days, I’ve tried to reconstruct the events that led to the sudden shutdown of Convoy. I’ve spoken with insiders at the company to try to understand how the rocket ship could suddenly run out of fuel and crash back to earth.
According to insiders, in late 2021, Convoy stopped offering incentives to shippers to join its platform. The company recognized that investors were getting weary of the incentives that drove early growth and expected to see expanding margins at increased levels of scale.
For the past two years, Convoy had higher-than-market gross margins.
In 2022, the company had 17.7% gross margins and year-to-date had 18.1% gross margins. It wasn’t easy for the company to achieve these levels and it required the firm to back away from the practices that provided early growth.
In fact, Convoy walked away from shippers and blanked on many bids when they required margin sacrifice. Industry veterans will recognize that this sounds like Convoy had become a “real logistics company” with discipline in its bidding process and that would be correct.
The problem was that sacrificing load volumes also came at the cost of hypergrowth. The company assumed that the high levels of sustained margin would be more attractive to future investors, but that wouldn’t be enough. After all, part of the growth story was now gone.
Convoy had a very sophisticated data science model and compared its buy-and-sell rates against industry benchmarks. The company was consistently buying below the averages and had locked in higher rates on contracts when rates were much higher. It was marginally profitable on the major long-haul lanes, but made far greater profits on the regional and short-haul lanes, with high win rates.
According to the insiders, the company was able to achieve this because it had a strong data science and engineering team.
But that is also partially to blame for its ultimate demise.
A very large percentage of Convoy’s budget was allocated to technology engineering and data science. The amount was far greater than would be typical of a company of its size. Additionally, when capacity was super tight during COVID, Convoy went forward with a plan to lease approximately 4,000 trailers that were a part of its drop-and-hook program.
In early 2022, everything seemed to be going right for Convoy.
Although the freight market was entering a recession, few expected a significant deterioration in the freight economy. Convoy completed a capital raise and had just completed a fully built-out version of its platform, which offered fully digital brokerage.
According to internal data, the company’s platform achieved 98% automated load matching of all loads (true pricing, negotiation and matching in the open marketplace) via its mobile or web apps and 99% for local/city loads. Drivers used the Convoy app for every step of the job 96% of the time and on-time performance was 94% (within 30 minutes of appointment).
Convoy’s executive team believed the slowdown in freight would be short-lived. If the freight recession of 2019 was any guide, it would be a slowdown lasting for a quarter or two and then the market would revert back to the mean.
Plus, market volatility might be a good thing.
After all, for the past decade, each time the market was volatile, freight brokerages were able to expand market share and could optimize their margins during periods of instability.
Although the company’s very large investment in data science and engineering was high, it was instrumental in the company’s operating and product plans. Management was reluctant to take corrective actions, even though they acknowledged the high operating expenditures and fixed costs were a significant drag on the cash position. They believed that growth would present itself when things bounced back.
They also wanted to maintain margin discipline, so the company lost freight volumes from existing customers.
As the freight market continued to deteriorate throughout 2022 and into 2023, reality started to set in. Convoy conducted a series of layoffs, which reduced the operational support teams and an Atlanta brokerage office was closed.
The trailer program, which had been an early success, had become a significant cash drain by the second quarter of 2023. The daily cost of the trailers, when considering equipment, insurance and maintenance, became an anchor around Convoy’s profit/loss metrics.
Things continued to deteriorate. The freight market had not only entered one of the worst recessions in history, this freight recession was unlike any other in history.
Gross revenues dropped from $800 million in 2021 to a run-rate of $500 million in 2023. The Convoy hypergrowth story was over.
Investors, taking direction from public markets, started to sour on non-profitable businesses. Once ignored, unit economics became of utmost importance. Even though Convoy had demonstrated its model was able to achieve margins that were much higher than typical freight brokerages, it wasn’t enough.
Investors, who had previously been unaware or ignored the realities of freight markets, suddenly realized that freight markets were among the most volatile on the planet and that freight is a commodity — and thus capacity is fungible. After all, shippers could easily find alternatives to Convoy’s services with thousands of other freight brokers in the market.
The discounts and incentives that Convoy had offered in its earliest days to achieve scale didn’t guarantee shippers would stay loyal to Convoy when the market dynamics changed.
The blitzscaling model was broken.
It may have worked fine in times of a zero interest rate policy (ZIRP), but those days also were over.
Convoy was a victim of two realities: a failure to control its own destiny by relying on investors for funding and the violence and realities of the freight market, which are outside of anyone’s control.

(Photo: Jim Allen/FreightWaves) Broken valuation models
One assumption that almost everyone in the industry had is that Convoy had achieved enough scale that it would be impossible to kill it. After all, even if Convoy’s business model failed, someone would want to acquire it for the hundreds of millions in freight across the platform.
Silicon Valley insiders used to say that Convoy had achieved “escape velocity,” or the idea that the momentum of the business was so great that market gravity wouldn’t hold the company back.
But the business had raised too much money at valuations that defied reality.
There was a huge delta between how the VCs were bidding up digital brokerage valuations and how industry incumbents (or acquirers) looked at valuations.
Venture capital firms plan to eventually sell the businesses they invest in after the company has become very valuable. In order for VC firms that invested in Convoy to get a return, the company’s net revenues would eventually need to be of sufficient scale to overcome the operating expenses of the company, thus generating EBITDA.
After all, mature freight brokerages always sell for a multiple of EBITDA.
This meant that Convoy, the highest-profile venture-backed digital brokerage, always had a difficult task: to quickly scale the business to generate enough EBITDA to match its valuation using traditional norms. Otherwise, there would be a massive valuation reset down the line.
Convoy’s overfunding ultimately killed the business
Investors had greatly exaggerated Convoy’s valuation in their models and assumed the company was unstoppable, therefore, dooming the company by eliminating the option for a soft landing (death by overvaluation).
Here is the math. At Convoy’s last round of funding, the company was valued at $3.8 billion. It was generating $800 million in gross revenue. At 17% margins, that would equate to $136 million in net revenues.
All of the operating expenses are below this line.
Mature brokers sell on EBITDA, but there have been a number of high-growth, mid-stage brokers that have been acquired for net revenues. These firms have sold in the range of two to three times net revenues, which implies that Convoy should have been valued at around $272 million-$400 million at the time of its last funding. It was valued at 10 times more than it should have been.
When the freight market collapsed, the company had raised so much equity, but it also borrowed money from banks and other financial institutions, taking on a large amount of debt, including a $150 million line of credit from JPMorgan and $100 million in venture debt from Hercules Capital — that there was little flexibility in its capital structure to find alternatives.
The deterioration of Convoy’s revenues also meant that any metric used to value the company would require a significant rerating. In other words, a growth multiple isn’t possible.
The board had little incentive to provide bridge funding in order to get the company acquired for 1/20th of the valuation — or worse — of the valuation of its last round. After all, the investors behind the company had bought into a version of the Convoy story that appeared highly unlikely.
Additionally, the debt holders, traditionally more risk-averse, had zero incentive to fight to protect the company’s equity but wanted to avoid the company running completely out of cash.
After all, bankruptcy can be expensive.
That is why lenders have debt covenants in their deal structures — to ensure that in the event of a default the company’s assets can survive long enough to allow for a liquidation and wind-down.
In technology firms, this means that the servers must stay on long enough for prospective buyers to get a chance to conduct their due diligence and manage a transition of the tech stack to a new platform.
In recent days, with Convoy out of compliance with its loan covenants, the company’s lenders called in the note, instituting the wind-down process. It was sudden and unexpected for nearly everyone associated with the company.
Insiders tell me that the executive team had worked diligently for the past few months to find a buyer but ultimately ran out of options.
Industry incumbents have resented Convoy since its founding because of its ability to secure funding at unsustainable valuations, but that proved to be what ultimately killed the company.
Convoy’s story, while tragic for investors and insiders, should prove cautionary for other founders. Raising money at valuations that are well beyond market norms is appealing, but if growth slows and you’ve burned through the capital, early investors may lose their appetite for future investment.
In fairness to Convoy, it is not the only venture-backed digital brokerage to face this reality. There will be more failures in the freight tech space over the next few quarters.
Excess capital is rocket fuel in the early stages of growth and can provide a false sense of security, as it doesn’t force founders to build companies with traditional constraints. That is what happened with Convoy. Management didn’t respond fast enough to changing market conditions when aggressive cost-cutting was necessary. They also had a false sense of security that future investors or an acquirer would provide the ultimate backstop, neither of which happened.
As Convoy’s founders learned, there is such a thing as death by overfunding.
-
Gig work is the future
A continuous divide between whether a gig worker is in employee or an independent worker is expected to continue for some time.
Traditionally the most common form of work has been the employee-employer relationship.
That changed when people started being independent contractors and the 1099 model came into being. The entire intent of someone being a independent contractor means they are self-employed. They’re free to work when they want on their own schedule and and they are responsible to deliver the goals and objectives that they subscribe to as part of the contract they sign with their client. While an independent contractor gains these flexibilities, they give up certain protections such as health insurance, paid time off, workers compensation and other benefits.
However technology based employment has changed things in an extremely accelerated manner. There was practically no gig working before the likes of Uber. And we all know the pace at which gig work has expanded over the last almost two decades is anything but ordinary.
I have read a variety of forecasts projecting upwards of 51% of the US workforce being independent workers in literally the next decade or two.
A gig worker as originally intended was an individual who could use their skills or things to offer services on a part-time basis. This record the sharing economy. Over the last few years, this definition has completely changed. A large percent of our workforce has now become a full-time gig worker. And that is where lies the conundrum.
This calls for a significant shift not just in how we see the gig economy but also how this form of independent work is structured.
A gig worker is an evolved form of a contractor. Now there are two types of contractors.,.
1. People who step away from having a full-time employment because they wish for greater autonomy and flexibility in their lives. In most cases these individuals possess skills that are in high demand.
2. The other category of individuals are the ones who we traditionally called gig workers. These individuals are finding temporary employment through technology-based platforms. Not all gig workers are working full-time on gig platforms. There are a lot of people within that gig worker pool who are working only because the either have an interest or have available time and skills that they wish to monetize.
Traditionally anyone who’s working as an independent fails to receive the protections (health insurance, paid time off, accrued benefits etc) that are typically offered by employers to an employee. The reason employers cannot offer these benefits to independent contractors is because by law these benefits are limited only to those who satisfy the employer employee relationship test. By offering such benefits to contractors their tax classification comes into question.
While there maybe some independent contractors who work full-time on these gig platforms, they are not necessarily tied to any one platform. Mostly, they multitask between multiple platforms. And most of them prefer having the flexibility of clocking in and clocking out at will and on their own schedule. Such privileges are not available to an employee.
For the system to truly evolve and grow, how gig work is structured will change significantly from how it is done today.
Large organizations that rely on armies of gig workers to enable the services they offer will need to find a middle ground of providing protections to the gig workers. Why they may continue to be classified as an independent contractor, the legal framework will need to evolve to produce a structure where benefits can be provided to independent contractors without having them to be treated legally as employees.
-
We’re more creative while walking?
Many people have had their best ideas while walking—this Stanford study explains why…
https://www.apa.org/pubs/journals/releases/xlm-a0036577.pdf
(copy-pasted from a linkedin thread)
This is nothing new. 150+ years ago Charles Dickens used to walk many miles every day for inspiration.
He was a prodigious walker. Whether on his night walks through London, or tramping through the Kent countryside, Dickens clocked up a huge number of miles on foot. He is estimated to have walked twelve miles per day in just two-and-a-half hours.A good point…. The phenomenon has been known for some time – think of people pacing up and down when thinking. If I remember correctly (and I’m sure someone will put me right) engaging the motor cortex more generally “frees” the mind and facilitate creative non-linear thinking (it’s why many people experience having great thoughts in the shower and when shaving or putting on make-up first thing in the morning) … If it was good enough for Aristotle (and Dickens) then perhaps it is good enough for the rest of us. All the best
-
Simple workouts | Hanuman dand
Try to do 200 per day
The below is quite interesting (a bit gimicky but if you extract the actual asanas its quite valuable)
-
Pricing
Leading with low prices is anything but smart. Any businesses trying to lower their prices or advertise their low prices to build differentiation for themselves. The first starter consumer has when they see low prices is that you are likely also providing lower quality.
Leading with price is generally a bad idea. Spend your marketing dollars on shouting out your competitive advantage – An advantage that people will be willing to pray premium prices for.
Think about the advantage that Lexus has over Camry; it’s not price it’s something else
Nordstrom over JCPenney;
If you ever plan to lower price… Let that be an exclusive instance, a one time only offer. Make sure that your price reductions are not predictable. This means that don’t be lowering your price on every event or occasion.
Every time someone on your team wants to lower the price because you do not have a well-established position ask this question..
Would you rather they walk away saying “I wish we can afford their offering” or would you rather that they say “the price is so low, I wonder if the offerings are any good?”
Most people in business complain that their customers only care about price… That is true a lot of the times. Customers are very quick to bring up price differences because they do not clearly understand the difference between you and your competition. When they cannot quantify the difference in value they quickly call it out as a difference in price. It’s the same product at a different price. But the moment you can successfully explain how your product is different, there being a difference in price is only natural.
People on also very hesitant to raise prices when they’re competitors products are priced lower than them. The idea is to straddle your competition. Present a product which is similar quality to the competition and a slightly lower price than them. And have your standard product be priced higher than the competition and be very clearly better than the competition. You and your marketing team job is to explain value not to lower price. Marketing teams at lower prices aren’t really staffed with marketing people.
-
Everyone sells
Once upon a time, only certain people were in sales. Those few people sold so the time, the rest of us did stuff.
Then the world started to change and more of us started to work for ourselves – and because we became entrepreneurs we became salespeople too.
— from the book “To sell is human” by Daniel Pink